Planning for Health, Life, and Financial Protection
Guiding individuals and families through coverage options with clarity and care.
We provide guidance across health coverage, life insurance, and financial protection to help you make informed decisions.
health insurance
Access to Health coverage is foundational to financial stability. We help individuals and families evaluate their options based on eligibility, healthcare needs, provider access, benefits, and overall costs.
Medicare
Medicare is health insurance for people 65 or older. You may be eligible to get Medicare earlier if you have a disability, End-Stage Renal Disease (ESRD), or ALS (also called Lou Gehrig’s disease). Medicare coverage can include Original Medicare, Medicare Advantage, Medicare Supplement, and prescription drug coverage, depending on eligibility and availability. Choosing among these options may involve reviewing provider networks, prescription needs, out-of-pocket costs, travel preferences, and additional benefits. DIA helps Medicare-eligible individuals understand available options and compare coverage based on their personal healthcare needs and circumstances.
Learn MoreAffordable Care Act (ACA) "Obamacare"
Affordable Care Act (ACA) Marketplace coverage helps eligible individuals and families access health insurance through federal or state Marketplace programs. Depending on household income, family size, location, and other eligibility factors, some applicants may qualify for premium tax credits or other financial assistance. Coverage options vary by state, county, carrier, plan availability, and enrollment period. DIA helps clients understand Marketplace options, enrollment requirements, Special Enrollment Periods, and available coverage so they can make informed decisions based on their healthcare needs and circumstances.
Learn MoreSupplemental Coverage
Additional protection designed to complement your primary health coverage. Supplemental insurance may help address certain out-of-pocket expenses that major medical coverage does not fully cover, depending on the product and policy. Options may include dental, vision, hospital indemnity, accident, cancer, critical illness, and other ancillary benefits. Availability, benefits, limitations, and eligibility vary by carrier, product, state, and individual circumstances. DIA helps clients review supplemental coverage options and determine how they may fit alongside existing health insurance and broader protection needs.
Learn MoreTemporary Health Coverage Options
Temporary health coverage may provide limited, short-term protection for individuals who are between jobs, waiting for employer-sponsored coverage to begin, transitioning between plans, or experiencing another temporary gap in health insurance. These plans are not a substitute for comprehensive ACA-compliant coverage and may have important exclusions, benefit limits, underwriting requirements, or restrictions. Availability and plan terms vary by state, carrier, eligibility, and current regulations. DIA helps clients review temporary coverage options and understand how they compare with Marketplace and other health insurance alternatives.
Learn Morelife insurance
Life insurance provides financial support for dependents and outstanding obligations. Coverage selection depends on income replacement needs, long-term responsibilities, and financial goals.
Term Life
Term life insurance provides coverage for a defined period and is often used to help protect income, replace lost earnings, cover debts, or support family financial needs during working years. Premiums and eligibility depend on factors such as age, health, coverage amount, and policy term. DIA helps clients review term life options based on their protection needs and long-term financial goals.
Learn MoreWhole Life
Whole life insurance provides permanent coverage with fixed premiums, a guaranteed death benefit, and potential cash value accumulation, subject to policy terms. It may be considered by individuals seeking lifelong protection and greater predictability. DIA helps clients understand how whole life insurance may fit within broader protection, estate, or family planning objectives.
Learn MoreFinal Expense
Final expense insurance is designed to help families address funeral, burial, medical, and other end-of-life expenses. These policies generally provide smaller death benefits than traditional life insurance and may offer simplified underwriting, depending on the carrier and product. DIA helps clients compare final expense options based on budget, eligibility, and individual protection needs.
Learn MoreIndexed Universal Life (IUL)
Indexed Universal Life insurance provides permanent life insurance coverage with flexible policy features and potential cash value accumulation linked in part to the performance of a market index, subject to policy terms, caps, participation rates, charges, and other limitations. IUL policies are complex financial products and should be evaluated carefully. DIA helps clients understand available options, costs, risks, and long-term objectives before making a decision.
Learn Morefhgfg
financial protection
Planning for retirement income requires evaluating risk tolerance, liquidity needs, time horizon, income objectives, and how different financial protection strategies may fit within a broader retirement plan.
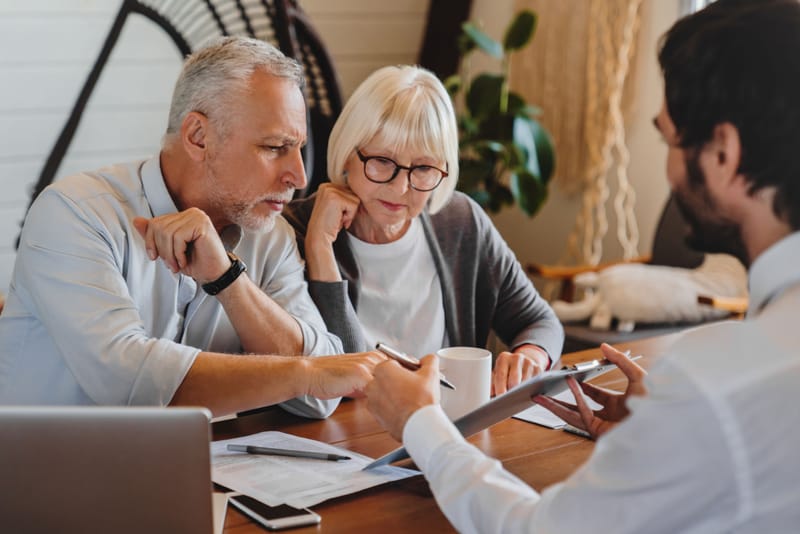
Annuities
An annuity is an insurance contract designed to help address long-term financial and retirement income needs. Depending on the product, annuities may offer principal protection, tax-deferred growth, and options for guaranteed income, subject to contract terms, fees, surrender periods, and carrier requirements. Different types of annuities involve different levels of risk, liquidity, and growth potential. DIA helps clients review available annuity options based on retirement goals, time horizon, liquidity needs, and overall financial circumstances.
Learn Morehow we evaluate coverage options
Before any recommendation is made, available options are reviewed carefully and explained clearly.
Eligibility
Program requirements and qualification rules are reviewed to determine which options may be available.
Personal Situation
Household structure, dependents, and personal circumstances are considered as part of the evaluation.
Health and Coverage Needs
Existing coverage, provider access, medications, and medical needs are reviewed to identify potential gaps.
Financial Situation
Income, financial responsibilities, and affordability are evaluated when comparing available options.
Long-Term Goals
Future objectives such as family protection, retirement planning, and financial security are considered.
Risk Considerations
Potential financial or health risks are assessed to ensure recommendations are complete, balanced, and transparent.
- You experience a major life event (marriage, divorce, birth of a child)
- Your income or financial responsibilities change
- You change jobs or lose employer coverage
- You approach retirement
- You develop new health needs or require ongoing care
- Your current doctors or medications are no longer covered
- You want to review protection for your family or dependents
- You want to evaluate long-term financial protection or retirement strategies
- Your current coverage no longer aligns with your situation
Periodic reviews help ensure your coverage remains aligned with your health needs, financial situation, and long-term goals.
The following disclaimer applies only to individuals seeking information about Medicare-related products:Dedicated Insurance Advisors LLC is a private insurance organization and is not affiliated with the United States government or the federal Medicare program. We do not offer every plan available in your area. Currently, we represent 17 organizations offering 219 products in your area. Please contact Medicare.gov, 1-800-MEDICARE, or your local State Health Insurance Assistance Program (SHIP) for information about all available Medicare options.
Dedicated Insurance Advisors LLC: +1 (832) 342-0894 | Fax: (888) 497-7651 | Monday-Friday, 9:00 a.m.-6:00 p.m. Central Time.
here, you can explore, compare, and enroll!
general information about product types
Health Insurance Marketplace
Explore how we help
Life insurance solutions for every stage of life!
Explore how we help
Extra protection that truly makes a difference!
Explore how we help
Annuities can help with numerous financial goals!
Explore how we help